A property UG is a German limited liability company used to acquire, hold, let or manage real estate. It offers a way to organise property investments within a corporate structure, but its suitability depends on more than low initial share capital. Financing, ongoing administration and the treatment of rental profits and future sales all matter.
Before setting up a property UG in Germany, consider how you intend to fund the company, manage its properties and use its profits. This guide explains the structure, formation process, costs and tax considerations, helping you assess whether a UG fits your long-term property strategy.
Key takeaways in 30 seconds
- A property UG is not a separate legal form. It is a UG (haftungsbeschränkt), a German limited liability company whose business purpose focuses primarily on acquiring, holding, letting or managing property.
- A UG is a corporation and is generally subject to corporate income tax and trade tax. However, companies that exclusively manage and use their own real estate may qualify for the extended trade tax deduction under § 9 No. 1, sentence 2 et seq. GewStG, provided the statutory requirements are met.
- A UG’s share capital can be below €25,000. It must be paid in full upon formation, and contributions in kind are not permitted when establishing a UG. In practice, extremely low share capital is often unsuitable for a property business.
- The formation process generally follows the same steps as any other UG: define the business purpose and articles of association, complete notarisation, open a business account, pay in the share capital, obtain commercial register entry and complete tax registration.
- A property UG does not automatically offer tax advantages. The deciding factors include the property strategy, financing, holding period, ongoing income, planned sales and whether profits remain in the company or are distributed to shareholders.
- Set up your property UG: Once you have defined the business purpose and planned property structure, you can form your UG digitally with beglaubigt.de and prepare the process from the formation documents through to the commercial register application.
What is a property UG?
A property UG is an Unternehmergesellschaft (haftungsbeschränkt) used for property-related business. It can, for example, acquire, hold, let and manage properties, provided these activities fall within its business purpose.
Legally, it is not a special type of property company, but a regular UG governed by the German Limited Liability Companies Act. The word “property” simply describes its business purpose. The same company law requirements therefore generally apply as to other UGs.
The structure is particularly relevant to founders who want to build a property portfolio within a limited liability company. Whether it offers tax advantages depends on the specific activities and tax arrangements.
Have you assessed whether a property UG is suitable for your plans? You can then start forming your UG digitally with beglaubigt.de and prepare the next steps, from the formation documents to the commercial register application.
Setting up a property UG: Advantages
Setting up a property UG can offer several advantages, particularly through tax incentives and flexibility under company law. A closer look at Germany’s tax and company law framework explains why a property UG may appeal to entrepreneurs and investors.
Tax advantages:
- Income tax considerations: Profits from letting and leasing property are treated as rental and leasing income under § 21 of the German Income Tax Act (EStG). Under certain circumstances, this income may benefit from allowances that directly reduce the tax burden. A property UG can significantly reduce its taxable income through depreciation, known as AfA, which recognises the decline in a building’s value over time. One example is straight-line depreciation for residential buildings, which is generally 2% per year.
- Option to charge VAT: Under certain conditions, a property sale can be made subject to VAT. This can be particularly advantageous when selling to another business entitled to deduct input VAT. It may make the property more attractive to the buyer and therefore increase its sale value.
- Trade tax: A property UG that exclusively manages assets and is not classified as commercial by virtue of its structure may, under certain circumstances, be exempt from trade tax. This depends on how its business activities are organised. The distinction between asset management and commercial activity is crucial, as commercial income is subject to trade tax.
Flexibility under company law:
- Limited liability: Like a GmbH, a UG (haftungsbeschränkt) offers the advantage of limiting liability to the company’s assets. This is particularly relevant to property investments, where the financial risks can be substantial. Shareholders are therefore protected against personal liability for the company’s debts.
- Low share capital: Compared with a GmbH, a UG can be established with minimum share capital of just €1. This makes a property UG accessible to smaller investors and property start-ups.
- Flexible management: A UG allows flexibility in its management and organisational structure. The company can therefore be adapted to the specific needs of the property market and its investors.
Practical example:
Suppose a property UG buys an apartment building for €500,000 and applies straight-line depreciation at 2% per year. This produces an annual depreciation allowance of €10,000, which can be deducted from rental and leasing income, effectively reducing the UG’s tax burden. If the property is subsequently sold after renovation, an option to charge VAT may also be available under certain conditions, potentially increasing its sale value.
What business purpose is suitable for a property UG?
The business purpose should describe as precisely as possible the property activities the UG intends to carry out. Depending on the business model, these may include acquiring, holding, managing and letting its own real estate.
Particular care is needed if the company intends to claim the extended trade tax deduction. Additional activities can affect whether the requirements are met. The business purpose should therefore be sufficiently specific under company law while also reflecting the intended tax structure.
For a company focused exclusively on its own property portfolio, possible wording might include “the acquisition, holding, management and letting of the company’s own real estate”. However, the wording should always reflect the actual business model and should be reviewed before formation where the structure involves sensitive tax considerations.
What taxes does a property UG pay?
A property UG is generally treated like other corporations for tax purposes. The relevant factors therefore extend beyond whether the company owns or lets property. They include the income it generates, any additional activities it carries out and how its profits are subsequently used. The frequently repeated claim that an asset-managing property UG pays a flat tax rate of only 15.83% is therefore an oversimplification.
Corporate income tax
A UG’s taxable profits are generally subject to corporate income tax. The solidarity surcharge is charged on top of that tax. At company level, business expenses and, where the statutory requirements are met, depreciation on buildings can reduce taxable profits.
The actual overall tax burden also depends on what happens to the profits afterwards. Retaining them within the company for further investment is different from distributing them to shareholders, which may trigger additional taxation at shareholder level.
Trade tax and the extended deduction
As a corporation, a UG is generally treated as a commercial business and is therefore also subject to trade tax. However, the extended deduction for property companies under § 9 No. 1, sentence 2 et seq. GewStG can be particularly relevant.
Where the statutory requirements are satisfied, the trading income attributable to managing and using the company’s own real estate can be deducted. However, the requirements are strict. Additional activities in particular can affect the company’s eligibility.
Before formation, it is therefore important to establish which activities the property UG will actually carry out and how its business purpose should be worded. The extended deduction should not be confused with a general exemption from trade tax for property UGs.
VAT
VAT treatment also depends on the specific activities. Letting real estate is generally assessed differently for VAT purposes from certain commercial letting services or property transactions. Under certain conditions, it may also be possible to opt to charge VAT.
For planned acquisitions, lettings and subsequent sales, the VAT implications of the specific business model should therefore be reviewed in advance.
Distributions to shareholders
Taxation does not necessarily end at company level. If profits are distributed to shareholders, additional tax may arise at shareholder level. A meaningful comparison between private property ownership and ownership through a company therefore requires more than comparing the UG’s corporate income tax rate with an individual owner’s personal income tax rate.
Whether a property UG is tax-efficient depends on the overall structure. Relevant factors include the holding period, financing, ongoing income, planned sales, additional activities and whether profits are distributed or reinvested within the company over the long term.
Property UGs: How to benefit from a 15.83% tax rate
As a corporation, a property UG benefits from a comparatively low tax rate on profits: it pays just 15% corporate income tax plus a solidarity surcharge of 5.5%, resulting in an effective rate of 15.83%. This taxation applies to profits—for example, rental income or sale proceeds after deducting expenses.
Compared with the top personal income tax rate of up to 45% on privately held rental property, this can produce a substantial tax saving, particularly for investors with higher incomes or growing property portfolios.
There is a further potential advantage concerning trade tax: property UGs that exclusively manage assets are not treated as commercial businesses for the purposes of the Trade Tax Act. Under § 9 No. 1, sentence 2 GewStG, trade tax does not apply to income from “the management and use of the company’s own real estate”. It is important that the UG does not engage in active commercial activities, such as extensive property development or short-term letting with additional services.
The conclusion: investors who use a property UG purely for asset management can secure a lasting effective overall tax rate of just 15.83%—a significant tool for building property wealth sustainably.
Setting up a property UG: What steps are required?
Forming a property UG involves several steps, explained in detail below:
- Choose the shareholders: First, determine who the shareholders of the property UG will be. They may be individuals or legal entities. It is important that all shareholders are of legal age and have legal capacity. They are recorded in the shareholder list.
- Draft the articles of association: The articles provide the legal foundation for the property UG. They establish key provisions, including the shareholder structure, allocation of profits and losses, management of the company and its dissolution. Having a lawyer prepare the articles is recommended.
- Register the company in the commercial register: The property UG must be registered with the competent local court. The following documents must be submitted: the notarised articles of association, a declaration of the shareholders’ legal capacity, a declaration that the share capital is adequate, a shareholder list and an extract from the shareholders’ civil status records.
(beglaubigt.de now offers this process entirely remotely and digitally. Find out more about the commercial register application.) - Open a business account: Once the company has been entered in the commercial register, it is necessary to open a business account for the property UG. All business transactions are processed through this account.
- Apply for a tax number and VAT identification number: A tax number must be requested from the tax office for the property UG. If the property UG is subject to VAT, it also needs a VAT identification number.
- Take out insurance: Suitable insurance is recommended to protect the property UG against risks. This might include public liability or professional indemnity insurance.
What requirements apply when forming a UG, and how can you avoid common mistakes? Our article on legally compliant formation steps and costs provides practical recommendations for a successful registration.
How much does it cost to set up a property UG?
The formation costs of a property UG are generally no different from those of any other UG (haftungsbeschränkt).
To establish a property UG, you first need share capital of at least €1. However, choosing a higher amount is advisable, as the UG will usually generate little or no profit during its first few years and its share capital serves as a financial buffer against liabilities.
You must also budget for formation expenses, such as notarial fees and commercial register fees. The exact costs can vary depending on the work involved and the location, and should be assessed individually.
The property UG’s ongoing costs must also be considered. These may include rent for office or business premises, employee salaries and insurance premiums.
Our guide, “Setting up a UG: Requirements, costs and legally compliant formation steps”, explains the general formation costs and additional requirements in detail.
Tax optimisation through loss relief for property UGs: Position in 2026
The corporate income tax rate for an asset-managing UG remains the same as for other corporations: 15% plus a solidarity surcharge of 5.5%, producing an effective rate of 15.825%. However, the loss relief provisions under §§ 10d and 8 KStG are particularly relevant from a tax planning perspective.
Subject to certain conditions, losses from managing, renovating or selling properties can be offset against profits in subsequent years. This allows a property UG, particularly during its early stages, to invest strategically in renovations or improvements without facing an immediate tax burden.
Important: Loss carryforwards can be offset without restriction up to €1 million. Beyond that amount, minimum taxation applies, meaning that no more than 60% of the remaining profits can be offset. The period currently available for using these losses is up to ten years.
Recognition always requires an active business operation in property management. Pure investment companies that generate income exclusively through passive activities do not benefit to the same extent.
This rule also makes the property UG an effective vehicle for tax-efficient investment in 2025, particularly for building wealth over the long term.
Comparing the tax burden: Property UG versus private ownership
Example 1: Buying property through a property UG
- An individual who already owns private property and wants to let it for tax advantages establishes a property UG.
- The property UG purchases an apartment for €200,000.
- It lets the apartment to tenants and receives rental income of €1,000 per month.
- The property UG pays corporate income tax at 15% plus a solidarity surcharge of 5.5% on the rental income, resulting in a tax rate of 15.83%.
- The property UG must therefore pay €183.30 in corporate income tax per month.
Example 2: Buying property privately
- An individual already owns private property and wants to purchase another apartment for €200,000.
- The individual lets the apartment to tenants and receives rental income of €1,000 per month.
- The rental income is taxed at the individual’s personal income tax rate, which can be as high as 45%.
- The individual must therefore pay €450 in income tax per month.
In this example, purchasing through a property UG would be financially advantageous for the owner because the lower tax rates result in less tax being paid.
However, a property UG must also meet certain requirements and has disadvantages, such as greater administrative and accounting work. The property tax, which remains applicable to property owners, is also relevant in this context.
When must a property UG become a GmbH?
There is no statutory obligation to convert a UG into a GmbH, or Gesellschaft mit beschränkter Haftung. A UG can therefore generally continue in that form indefinitely. However, there are several reasons why business owners might decide to convert their UG into a GmbH:

Holding structures: Parent companies and property UGs explained
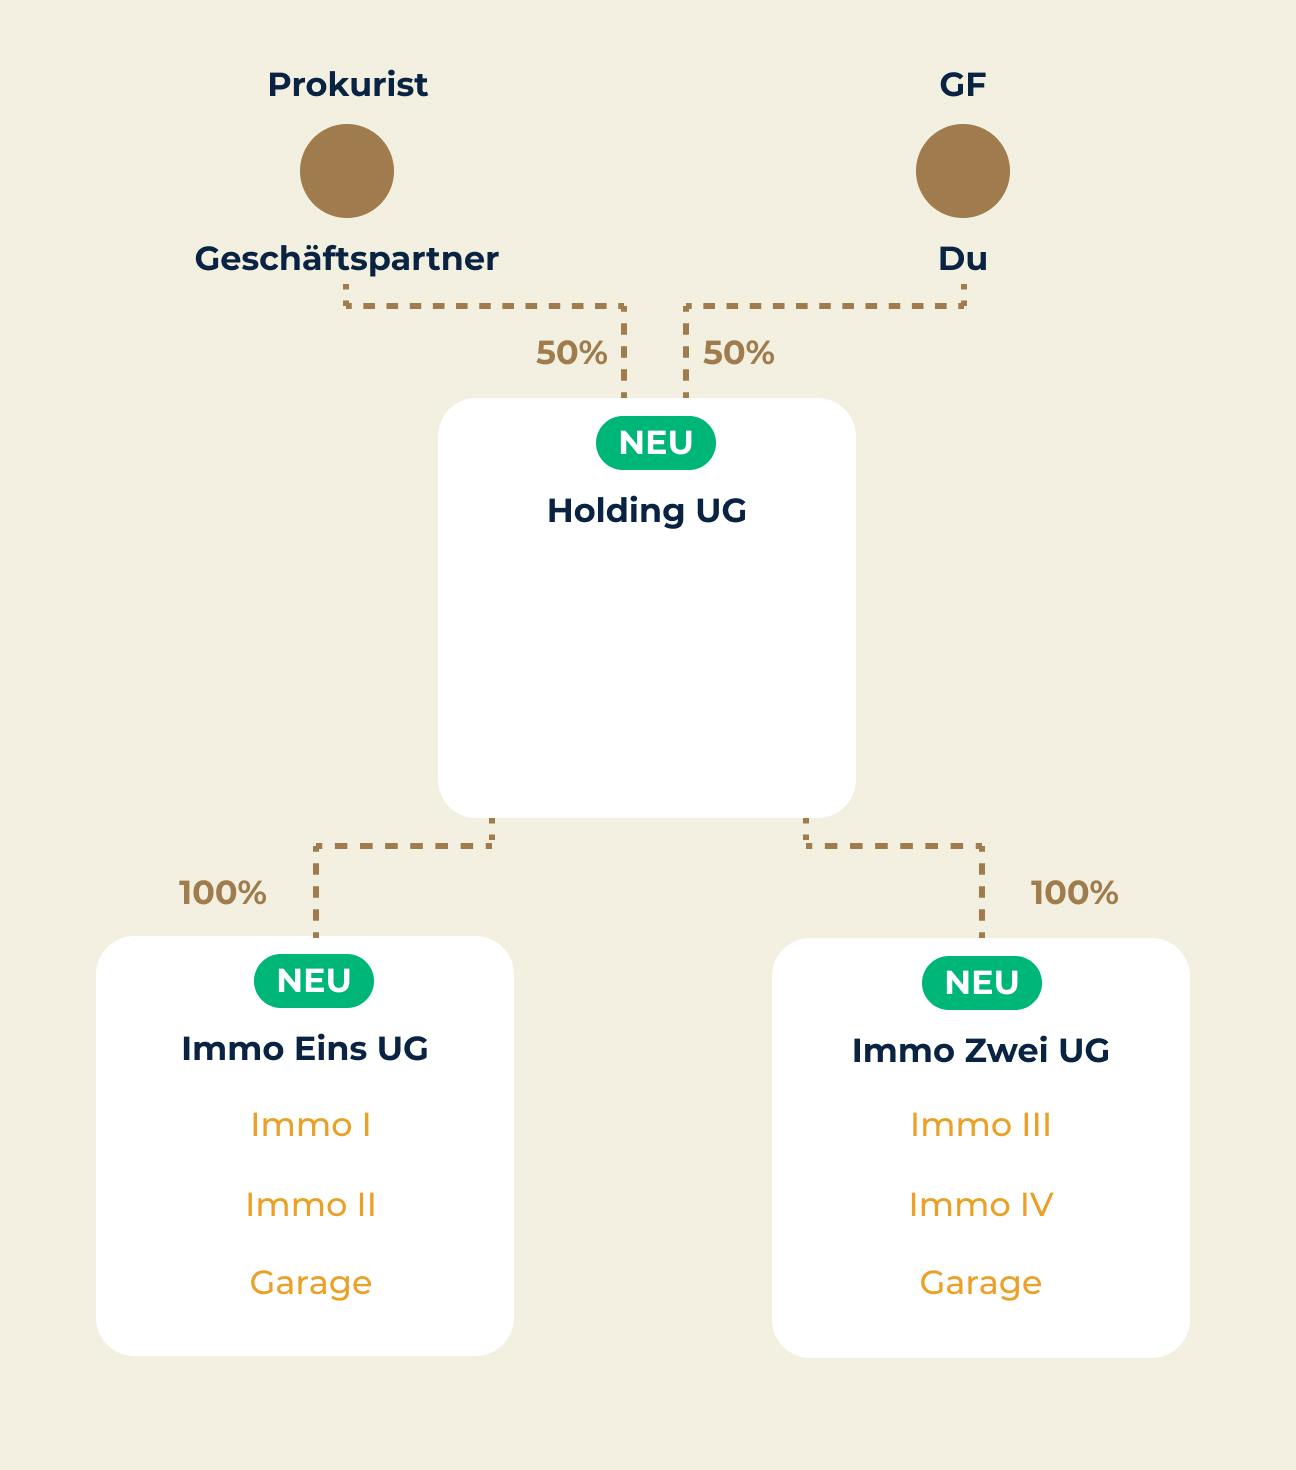
For a larger property portfolio, a holding structure may also be worth considering. In this arrangement, a parent company holds shares in one or more property companies, allowing different property portfolios or business areas to be kept legally separate.
Whether this structure makes sense from a tax and organisational perspective depends heavily on the portfolio, financing and long-term strategy. Our article, “Setting up a holding company: How to structure a business using a UG or GmbH”, explains how to establish such a structure.
Conclusion: Is setting up a property UG worthwhile for you?
Whether a property UG is worthwhile depends on several factors. A UG may appeal to entrepreneurs who want to build and manage a substantial property portfolio over the long term. Its corporate structure allows managing directors and shareholders to minimise liability risks and benefit from tax advantages.
However, forming and operating a UG involves various costs and obligations. These include notarial fees, commercial register fees and the cost of formation documents. Regular operating expenses, such as staffing, rent, insurance, taxes and loan payments, must also be considered.
If you have more capital available or prefer a GmbH structure from the outset, compare the two legal forms. Our article, “Setting up a property GmbH: Making effective use of tax advantages and limited liability”, explains the specific considerations for a property GmbH.
Before deciding to establish a property UG, carefully assess whether this company structure suits your objectives and whether you have the resources and funding needed to operate it successfully. A tax adviser or lawyer can help you reach a decision and explain the advantages and disadvantages of a UG compared with other business structures.
Have you assessed whether a property UG suits your plans? You can then start forming your UG digitally with beglaubigt.de and prepare the next steps, from the formation documents to the commercial register application.
FAQ about property UGs
What is a property UG?
A property UG is not a separate legal form. It is an Unternehmergesellschaft (haftungsbeschränkt) whose business purpose focuses on property. It can, for example, acquire, hold, let and manage its own real estate.
Can a UG buy property?
Yes. As a corporation, a UG has legal capacity and can generally acquire and own real estate in its own name. The planned acquisition and management of property should fall within the company’s business purpose.
How much share capital does a property UG need?
The capital requirements under § 5a GmbHG apply. The share capital must be paid in full before the commercial register application is submitted, and contributions in kind are not permitted upon formation. For a capital-intensive business such as property investment, the actual funding should not be based solely on the statutory minimum.
Does a property UG pay trade tax?
As a corporation, a UG is generally subject to trade tax. However, if the company exclusively manages and uses its own real estate, it may qualify for the extended trade tax deduction under § 9 No. 1, sentence 2 et seq. GewStG, provided the statutory requirements are met. Certain additional activities can affect eligibility.
Must a property UG later be converted into a GmbH?
No. A UG can generally remain a UG indefinitely. However, under § 5a GmbHG, it must allocate part of its annual net profit to a statutory reserve. A subsequent capital increase to the GmbH threshold is possible, but is not automatically required.
Property UG or property GmbH: Which is better?
This depends particularly on the available capital, financing, market perception, property strategy and long-term business plans. A UG allows you to start with less share capital, whereas a GmbH has subscribed capital of €25,000 from the outset.
Ready to take the next step? Set up your property UG with beglaubigt.de and prepare the formation process digitally.
Sources
- § 5a GmbHG — Unternehmergesellschaft (haftungsbeschränkt): Full payment of capital, contributions in kind and statutory reserves
- GmbHG — German Limited Liability Companies Act
- § 9 GewStG — Extended trade tax deduction for managing and using a company’s own real estate
- § 23 KStG — Corporate income tax rate
- Körperschaftsteuergesetz (KStG) — German Corporate Income Tax Act
- Gewerbesteuergesetz (GewStG) — German Trade Tax Act
- § 19 GmbHG — Payment of capital contributions
- § 7 GmbHG — Registration application and capital contributions